FHA-Insured HECM · Homeowners 62+
Your home has been paying you back for years. Here is how to collect.
A reverse mortgage turns part of the equity you already own into cash, a line of credit, or monthly income — without a mortgage payment and without giving up the deed.
How much could you access?
Five questions · about 60 seconds · no credit check, no obligation
How old is the youngest homeowner?
If you own with a spouse or partner, use whichever of you is younger — that is the age the program uses.
Is this your primary home?
A reverse mortgage can only be placed on the home you actually live in for most of the year.
What is your home worth today?
Your best estimate is fine. Nothing here is binding and no credit is pulled.
Any existing mortgage is normally paid off first, out of the proceeds. That is usually the point — it is what ends the monthly payment.
Worth asking. If your rate is low, paying that loan off may be the wrong move — and there is a version of this that leaves it alone.
What would this money be for?
There is no wrong answer. It helps us point you at the right structure.
Where should we send it?
Robert reviews these personally. No call centre, and your details are never sold to a lead network.
No credit check. This is not an application and not a commitment to lend. Estimates are illustrations only — see the disclosures at the bottom of this page.
Got it — your estimate is on its way.
Robert reviews every one of these himself and calls back the same business day. If you would rather not wait, call now and skip the queue entirely.
Call 631-926-0592 Or book a time that suits youThat didn't go through
Something on our end dropped the connection and your details were not sent. Please call directly — it gets handled immediately.
Call 631-926-0592 or email rerath@unitedmortgage.com- You keep the title. The home stays yours.
- No monthly mortgage payment for as long as you live there.
- Federally insured, and you can never owe more than the home is worth.

It is a loan. That is the honest version.
Not a government benefit, not a sale of your home, and not free money. A reverse mortgage lets you borrow against equity and defer every payment until you leave the house — which is powerful, and is also exactly why it deserves a careful look rather than a quick yes.
You still own it
Your name stays on the title. You can sell whenever you like, leave the home to your children, or refinance out of it. The lender holds a lien — the same thing your current mortgage company holds today.
The payment stops
If you still have a mortgage, it is paid off at closing out of the proceeds. For most borrowers that single change — several hundred to a few thousand dollars a month back in the budget — is worth more than the cash.
You cannot owe more than it sells for
HECMs are non-recourse. If the balance ever exceeds the home's value, FHA insurance covers the difference. Your heirs are never on the hook for a shortfall, and neither is your estate.
Four steps, about six weeks
Nothing is binding until you sign closing documents, and you can stop at any point along the way at no cost.
A real conversation
Twenty minutes on the phone. What you own, what you owe, what you are trying to solve. You will hear plainly whether this is a good fit — including when it is not.
Independent counseling
HUD requires a session with a counselor who does not work for us and is not paid by us. Roughly $125–$200, sometimes free. We think it is the best consumer protection in lending.
Application & appraisal
An FHA appraisal sets the value. A financial assessment confirms you can keep up with taxes and insurance. This is where the real numbers replace the estimates.
Closing, then the money
Any existing mortgage is paid off first. What is left comes to you as a lump sum, monthly payments, a growing line of credit, or a combination. You have three days to change your mind.
The number that matters is not the one you expect
Two homeowners with identical houses can qualify for wildly different amounts. Age does most of the work, and the expected interest rate does most of the rest.
The four things people get wrong
Almost every objection we hear traces back to one of these, and all four have been false since the program was reformed.
No. You hold the title exactly as you do now. The lender records a lien, which is what every mortgage lender does. When the loan ends, the home is sold or refinanced, the balance is paid, and anything left over belongs to you or your heirs.
They cannot. A HECM is non-recourse: the home is the only asset the lender can look to. If the balance exceeds the sale price, FHA insurance absorbs the difference. If the home is worth more, your heirs keep every dollar of it.
Most borrowers do not. An existing mortgage is simply paid off at closing from the proceeds — that is the most common reason people do this. You need enough equity to cover the payoff, not a clear title.
Loan proceeds are borrowed money, not income, so Social Security and Medicare are unaffected. Needs-based programs — Medicaid and SSI — are a real consideration, because money left sitting in your account at month end can count as an asset. That is solvable with timing, and worth raising early.

The goal is staying put
Almost everyone who calls wants the same thing: to stay in the house, on their own terms, without the payment. Whether this is the right way to get there is what the conversation is for.
This usually works well when…
- You intend to stay in the home for the long haul.
- A mortgage payment is squeezing a fixed income.
- You have substantial equity and thin liquid savings.
- You want a standby line of credit that grows — a genuinely underrated use.
- Delaying Social Security to 70 would pay off, if you can bridge the gap.
Think hard, or walk away, when…
- You may move within five years. The upfront costs will not have earned back.
- Leaving the house to your children unencumbered is the priority.
- Taxes and insurance are already a struggle — this does not fix that, and default is real.
- Health is failing and a care facility is likely within a year or two.
- Someone is pressuring you to take the cash and buy something with it.
Not sure which column you are in? Eight real situations with a straight answer for each, or read the unhedged case against before anything else.
You can also compare it against a HELOC and downsizing — sometimes those win — or see what changes in your state.
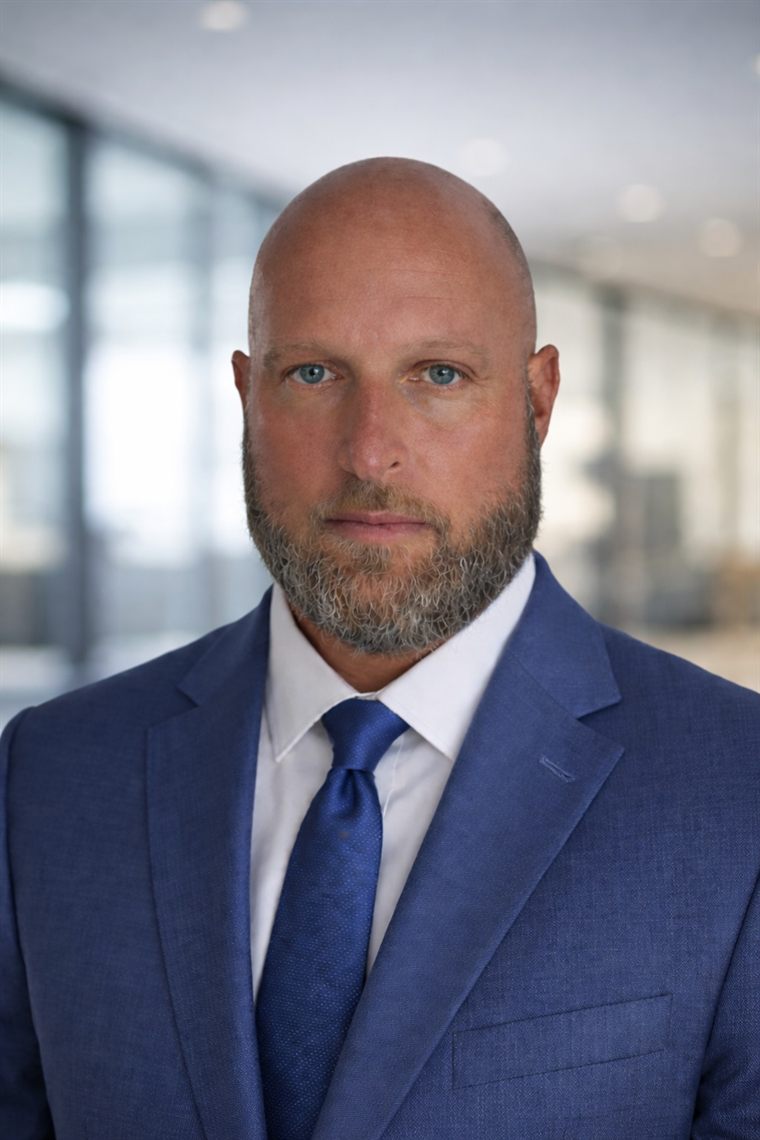
The person who answers
You will be talking to Robert
Not a call centre, not a rotating queue, and not a lead form that gets sold to four lenders who all ring you at dinner time. One licensed originator, on the phone, who has been doing this since 2004.
Expect to be told when a reverse mortgage is the wrong answer — roughly half the people who call should not take one, usually because they may move within a few years or because a conventional refinance would cost them far less. Hearing that is the point of the call.
Bring your children if you like. It usually makes for a better decision, and they are welcome to ask the awkward questions.
Questions people actually ask
What happens if I move out or go into care?
The loan becomes due once the last borrower has not lived in the home as a principal residence for twelve consecutive months. A short hospital stay or rehab does not trigger it. If the move is permanent, the home is sold, the balance is paid from the proceeds, and anything left belongs to you or your estate.
Can I still sell the house?
Any time, without penalty. You pay off the balance from the sale like any other mortgage and keep the rest. There is no prepayment penalty on a HECM — you can also make voluntary payments to hold the balance down if you want to.
What if my spouse is younger than 62?
They can be listed as an eligible non-borrowing spouse. The loan is calculated on their (younger) age, which reduces the proceeds, but they are protected: if you die first, they can remain in the home for life provided they keep up with taxes, insurance and upkeep. Getting this designation right at application is critical — it cannot be fixed afterwards.
Do I need good credit or a certain income?
There is no minimum credit score and no debt-to-income cutoff in the way a normal mortgage has one. There is a financial assessment: HUD requires the lender to check that you have the means and the history to keep paying property taxes and homeowners insurance. Past trouble does not automatically disqualify you — it may mean part of the proceeds is set aside to cover those bills, which is called a LESA.
How much does it cost to find out if I qualify?
Nothing. The estimate on this page is free and takes no credit pull. The first real cost is the appraisal, and that only comes after counseling, after you have seen your actual numbers, and only if you decide to proceed.
Ask a real question, get a real answer
You do not need to be ready to apply. Most people who call are still deciding whether this is even the right idea — and quite often it isn't. You will be told so.
- No credit pull to start. Nothing here touches your credit report.
- You speak to Robert — not a rotating pool of call-centre reps.
- Bring your family. Adult children on the call are welcome and usually a good idea.
- Your information stays here. Never sold to a lead network. Ever.
Send a question
Answered by a licensed originator, usually within a few hours.
Got it — talk soon.
Robert reads every one of these himself and replies the same business day. If you would rather not wait, call now and skip the queue.
Call 631-926-0592 Book a time insteadThat didn't go through
Something on our end dropped the connection and your details were not sent. Please call or email directly — it gets handled immediately.
Call 631-926-0592 or email rerath@unitedmortgage.com · try the form again